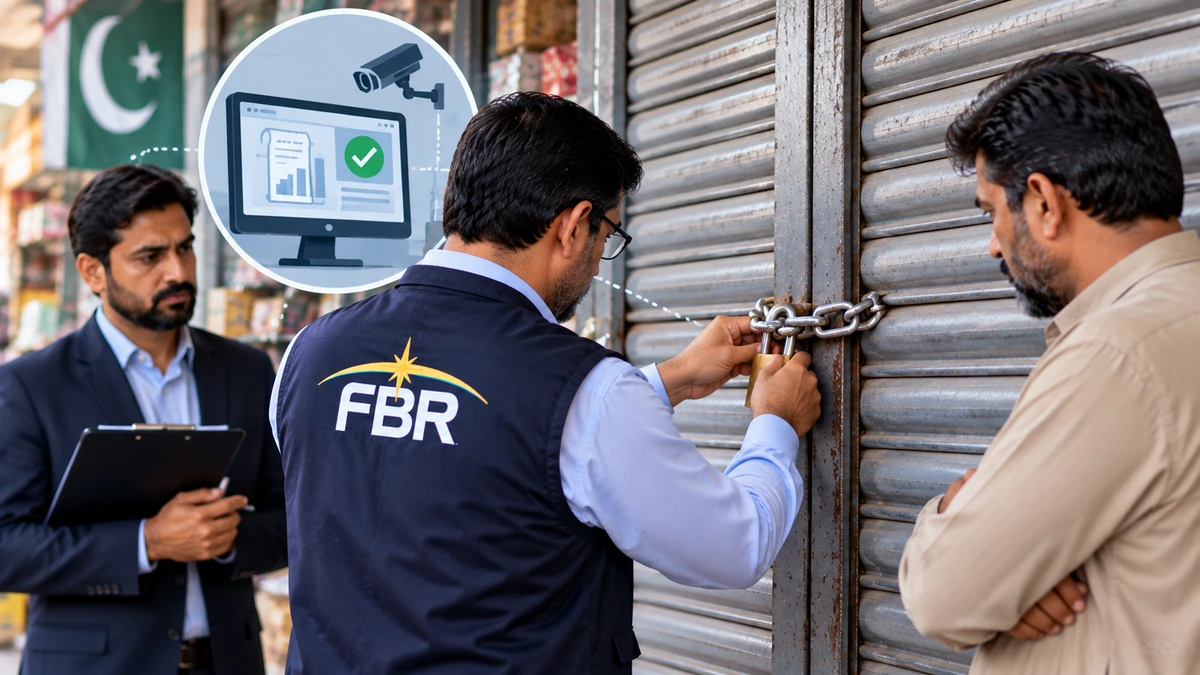
The Federal Board of Revenue has introduced a procedure allowing Inland Revenue officials to seal business premises where a person required to integrate with prescribed electronic monitoring systems fails to do so.
The new framework covers businesses subject to electronic monitoring, tracking or identification of production, sales, clearance, stock and related activities through systems including production monitoring, video surveillance, video analytics, digital-eye technology or other mechanisms prescribed by the FBR.
The FBR currently lists SRO 1662(I)/2026 as covering electronic monitoring of specified goods and the seizure or confiscation of non-compliant goods.
Current reporting on the notification says the sealing procedure can apply where a person required to integrate a business with the FBR or its computerised system fails to connect through the prescribed monitoring mechanism.
The rules are relevant to sectors already brought under electronic production-monitoring requirements, including textile and spinning units, but the procedure is not limited to those industries.
It can apply to registered persons or classes of registered persons, manufacturers or classes of manufacturers, goods specified under the relevant sales tax provisions, and other taxable goods that the FBR brings within the system through notification.
The measure gives the tax authority an enforcement mechanism where prescribed electronic monitoring is required but a business does not integrate as directed.
The rules also address goods produced, removed, transported, supplied or otherwise dealt with outside required monitoring arrangements.
Where specified taxable goods are handled without the required Production Monitoring System, production-monitoring equipment or other prescribed mechanism, or without required tax stamps, banderoles, stickers, labels, barcodes or other identification devices, the goods can become liable to seizure and confiscation.
According to current reporting on the notification, a vehicle or other conveyance used to move such non-compliant goods can also be seized and, following adjudication, confiscated.
The framework forms part of a broader FBR push to use electronic systems to record economic activity and strengthen enforcement in sectors where production, stock and sales can be monitored digitally.
For affected businesses, the practical significance is that failure to comply with a mandatory integration requirement can now move beyond a reporting or registration issue and lead to physical enforcement against premises or goods under the prescribed procedure.
The exact application will depend on whether a business, manufacturer, class of taxpayer or category of goods has been brought within the relevant electronic monitoring requirements.
Businesses not subject to a prescribed integration requirement are therefore not automatically covered simply because the new procedure exists.
The measure should also be distinguished from ordinary digital invoicing requirements. The notification concerns prescribed monitoring, tracking and identification systems for specified activities and goods, with enforcement tied to the particular requirements imposed by the FBR.
The new procedure adds sealing, seizure and confiscation mechanisms to the tax authority’s expanding electronic compliance framework, increasing the consequences for businesses that are formally required to integrate with monitoring systems but fail to do so.